

Summary
Financial relationship management (FRM) is accounts receivable software built around the customer relationship, not only the invoice: it combines reminder automation, payment behavior tracking and communication history in one record, the way a sales CRM does for the sales pipeline. It differs from a plain CRM in what it tracks: payment behavior and invoice status, not deals.
- Who coined it: Financial relationship management is a category name that the vendor Upflow uses for its own product, not a formal industry term with one fixed definition.
- FRM vs CRM in one line: A sales CRM tracks the deal before the invoice; an FRM system or accounts receivable CRM tracks the customer after it.
- Paidnice angle: Paidnice covers reminders, statements, a payment-history score from 1 to 100 per customer and optional late fees in one record, on Xero and QuickBooks Online.
What is financial relationship management?
Financial relationship management (FRM) is a category name that the accounts receivable vendor Upflow uses for its own product, not a formal industry term with one fixed definition. In practice it means running accounts receivable as a customer relationship: every reminder, statement and fee follows what you know about that customer's payment history.
The term belongs to B2B accounts receivable. It is separate from the Financial Risk Manager qualification, and separate from the CRM software that banks and wealth managers use for their clients. An FRM system, also called a finance CRM, sits on top of your accounting system. To pick one you need three things: the parts to look for, the questions to ask your team, and a checklist for vendor calls.
Accounting systems such as Xero and QuickBooks Online record what happened: the invoice, the payment, the balance. They are not built to manage what happens next.
A sales CRM does not fill the gap. It stops at the signed deal and holds no invoice data. FRM covers the period after the sale. The financial relationship management page shows how Paidnice does it for businesses on Xero and QuickBooks.
The work exists because invoices miss the due date. Xero Small Business Insights measures how often.
| Country | Paid late | Year on year |
|---|---|---|
| Australia | 4.3% | -2.7 pts |
| New Zealand | 5.1% | -0.5 pts |
| UK | 8.3% | -0.9 pts |
| US | 8.3% | -0.1 pts |
| Canada | 11.4% | +0.8 pts |
Source: Xero Small Business Insights, June 2026. See the full data on the Paidnice accounts receivable statistics dashboard.
That share is the queue the software has to clear.
The four parts of a financial relationship management system
An FRM system has four parts: customer context, segmentation, adaptive workflows, and finance, sales and support working from the same record.
Customer context
Payment history, notes, call outcomes, open disputes and the outstanding balance sit in one place for each customer.
- In Paidnice every contact carries a payment-history score from 1 to 100
- The score moves as the customer's behavior changes
- Notes and call outcomes sync to the invoice in Xero
Segmentation
Customers go into groups by payment behavior, size or risk, and each group gets its own policy.
- Inside a policy, the message changes with the age of the invoice
- Look for a system that runs several policies at once
Adaptive workflows
The schedule changes when the facts change.
- If a customer gives an expected payment date, collection pauses until that date
- Collection resumes if the invoice is still unpaid
- One disputed invoice comes out of a policy while the other invoices continue
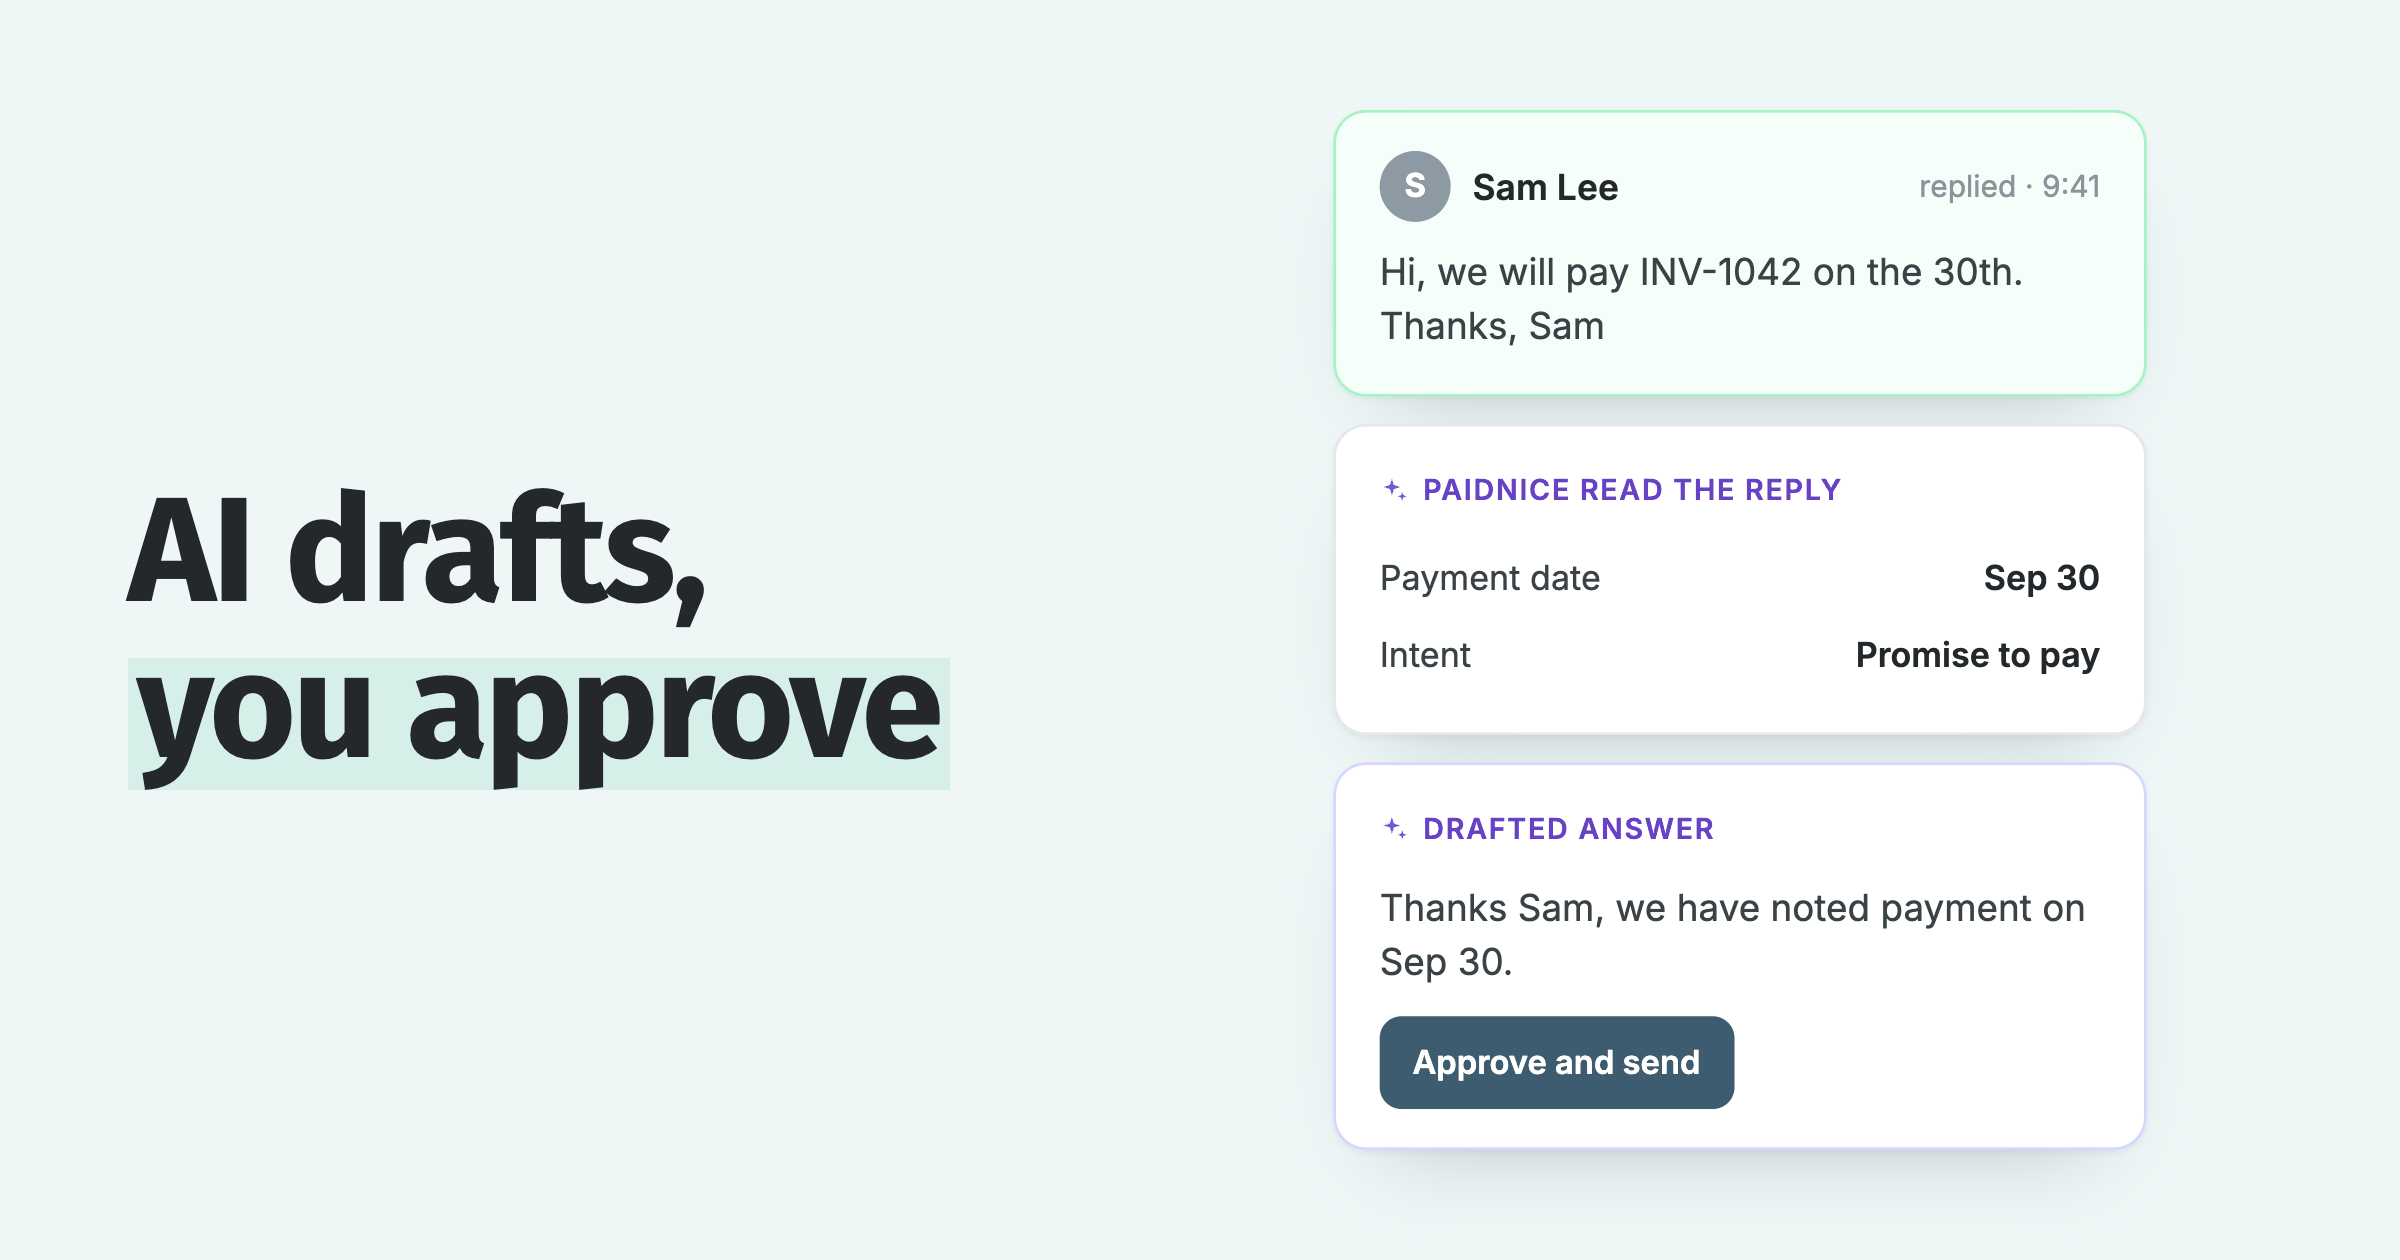
- An approval step lets a person check each action before it goes
Finance, sales and support in step
Sales and support see late payment, an early sign of churn risk, in the tool they already use.
- An escalation is assigned to a named person
- A mention in a note sends that person a notification
- Reminder emails log to the CRM through a BCC address (HubSpot, Pipedrive, Salesforce)
- Alerts go to Slack or Microsoft Teams by webhook
What is the difference between FRM and CRM?
An FRM system or accounts receivable CRM tracks the customer's financial relationship: payment behavior, invoice status and promises to pay. A sales CRM tracks the customer's buying relationship: deals, pipeline and renewals. The data, the users and the goal are different.
The score is the clearest example of the split. A sales CRM holds a deal stage. An FRM system holds a payment-history score: Paidnice rates every customer from 1 to 100 on their own payment history with you, and shows the score against the contact wherever it appears in the app, so the reminder sequence and the fee policy can follow it.
| CRM | FRM | |
|---|---|---|
| Primary focus | Leads, deals, pipeline | Invoices, payments, terms |
| Core user | Sales and marketing | Finance and credit control |
| Data it holds | Contacts, deal stages, emails | Invoices, payment history, notes, disputes |
| Goal | Win and grow revenue | Collect revenue on time, keep the customer |
| Terms enforcement | None | Depends on the vendor. Ask. |
The two systems work together. An FRM system does not replace your CRM. For the opposite question, whether you need FRM or plain automation, read financial relationship management vs accounts receivable automation. For the wider software category, read the guide to the accounts receivable CRM.
What changed by 2026
Three things changed between 2024 and 2026: AI answers now define the term, AI agents do collection work, and payment-history scoring is a standard feature to ask for.
AI answers define the category
Search for the term and an AI Overview gives a definition with four pillars before any vendor page.
Use it as the baseline, then ask each vendor what they do beyond it.
AI agents do collection work
Some vendors now sell AI agents that read customer replies, draft responses and escalate.
The buying question is control: does a person approve each action before it goes to your customer?
Payment-history scoring is expected
A score built from how each customer has paid you is more useful for daily collection work than a static risk label.
Ask where the score shows, how often it updates, and whether it can drive segmentation.
How to assess your needs for an FRM or finance CRM
Answer three sets of questions with your team before any vendor call: current pain points, growth goals and resources. The answers become your requirements.
What are your current pain points?
Look at the limits of your current process. Xero and QuickBooks account well for what happened. As invoice volume grows, the gaps show in collection: inconsistent follow-up, no record of who said what, and no view of which customers are getting slower.
Questions to copy and paste:
- Where are the blind spots in our current AR process, and what insights would help us improve collections?
- Do we have a clear understanding of each customer's payment behavior and risk level?
- What areas of our receivables process are taking the most time for our team to manage manually?
- Are we seeing recurring late payments? If so, what might be causing these delays?
- How effective is our current system in reaching the right person at the right time to ensure timely payment?
- Do we lack visibility into customer payment patterns or trends that could help us be more proactive?
- Are there specific customer segments that are consistently challenging to manage or follow up with?
What are your future growth goals?
Look at the tools and reports you use today. Ask if they can handle more accounts, international customers or new payment schedules. A system you pick now must still fit at two or three times the invoice volume.
Questions to copy and paste:
- How well can our current systems handle an increase in transaction volume or client base?
- Do we expect to expand into new markets or regions, and what unique AR requirements might those bring?
- Will our payment terms or schedules change as we grow, and can our existing tools support these changes?
- Are there revenue or growth targets that require us to improve our cash flow consistency or speed up our collection process?
- How will our AR process need to adapt if we expand our service lines or product offerings?
What resources do you have?
Look at your team's workload. If manual follow-up uses time that the team needs for other work, automation gives that time back. If the team is small, setup time matters as much as features.
Questions to copy and paste:
- What portion of our team's time is currently spent on manual follow-ups or routine tasks?
- Do we have the resources to implement and maintain an automated system, or do we need one that's quick to set up?
- Are we losing time or efficiency due to data silos between accounting, sales, and finance teams?
- What strategic initiatives could we focus on if we freed up time currently spent on manual AR tasks?
- Do we need a solution that can scale up without adding additional team members?
What do most FRM definitions leave out?
Check two things most FRM definitions leave out: what the system does when a customer breaks your terms, and how well it fits the accounting system you already use.
Enforcement. Communication alone has no consequence for a late payer. Check that the system applies late fees and interest by rule, sends statements on a schedule, and runs escalations such as a phone call task, a stop on credit or a template legal letter. Late fees are leverage: applied automatically, waived deliberately. If you run a fee policy with exemptions and approvals, see the late fee manager.
Accounting-system fit. The FRM system must read and write to your ledger with no spreadsheet between them. Ask if it picks up invoices that were already open on the day you connect. Paidnice does. Ask if email and SMS reminders send from your own domain, so the customer sees your name on every message.
Credit limits. If you give customers credit limits, ask if an escalation can trigger on a customer's total balance or on a credit-limit breach. The credit management software page covers how to manage credit you have already given.
How do you judge usability, support and room to grow?
Judge an FRM system on three practical tests: your team must be able to run the system without training courses, get help in its own time zone, and stay on the same system as invoice volume grows.
Ease of use and support. Ask for a live account with your own data. Check how account managers outside finance get access, and what onboarding help and support hours the vendor gives in your first month.
Growth. Check how the price changes as you grow. Some vendors price on your annual revenue, some on users, some on invoice volume. Check that you can add entities, currencies and integrations later with no move to a new platform.
FRM buying checklist: questions to ask vendors
Take these questions to every vendor call. They cover integration, automation, enforcement, scale, usability, support and security.
Integration and accounting-system fit
- Does this system integrate with Xero, QuickBooks, or other accounting software we're already using?
- Can it connect with other platforms we may implement in the future, such as CRMs or payment processors?
- Does it allow two-way data syncing to ensure accuracy across platforms?
- Does it pick up invoices that are already open when we connect, or only new ones?
- Do notes, call outcomes and fees write back to the accounting system?
- Do reminders and statements send from our own domain?
Automation
- What specific automation features are included? Can we set unique follow-up cadences based on customer segments?
- Are reminders, escalation paths, and fee structures customizable to suit varied payment behaviors?
- How flexible are the automation options? Can the system adjust reminders based on customer actions (e.g., partial payments)?
- Can collection pause until an expected payment date, then resume if the invoice is unpaid?
- If the system uses AI agents, does a person approve each action before it goes to a customer?
Enforcement of terms
- Can the system apply late fees and interest automatically, by customer group?
- Is the fee recorded as an invoice on our ledger, and can we choose Draft or Approved?
- Can we set a number of days overdue before a fee applies?
- Can we waive or credit a fee inside the system, and take one disputed invoice out of a policy?
- Does it send customer statements on a schedule, including consolidated statements for parent and child accounts?
- What escalation steps exist, who are they assigned to, and can they trigger on total balance or a credit-limit breach?
- Is there a report of fees charged against fees collected?
Scalability
- How well does the system handle increased transaction volumes or customer base growth?
- Will additional transaction volume incur higher fees or require a service plan upgrade?
- If we expand internationally, will the system support new currencies and localized payment terms?
- Is the price based on invoice volume, users or our revenue?
Usability and customization
- Is the interface user-friendly, especially for team members unfamiliar with FRM systems?
- How much customization is available for payment terms, reminder schedules, and communication templates?
- Can non-finance team members access relevant parts of the system if needed, with appropriate security?
Support and onboarding
- What onboarding services are provided, and are they included or an added cost?
- What support channels are available, and during what hours?
- Are there premium support plans with faster response times, should our needs increase?
Security and compliance
- Does the system comply with relevant industry standards and international financial regulations?
- What measures are in place to protect customer and financial data?
- Are regular security updates and data backups included?
Frequently asked questions
Short answers on what FRM is, how it differs from a CRM, and when plain accounts receivable automation is enough.
What is financial relationship management (FRM)?
Financial relationship management is an approach to B2B accounts receivable. The finance team keeps the payment context for each customer in one place and uses it to decide each reminder, statement, fee and escalation. The aim is on-time payment with the customer relationship intact.
What is CRM in finance?
In a B2B finance team, a finance CRM is a system that holds the customer record for the period after the invoice: payment history, notes, disputes and messages. In banking and wealth management the same phrase means client management software for advisors, which is a different product.
Do I need FRM software or accounts receivable automation?
If every customer can get the same schedule, accounts receivable automation covers it. If customers need different treatment, and sales or support need to see payment status, you need the FRM parts too. The comparison post has a decision list by business size.
Next step
Answer the three question sets with your team, then take the checklist to two or three vendors that connect to your accounting system.
If you run Xero or QuickBooks, start with financial relationship management in Paidnice. You can connect your ledger and see the payment-history score against your own customers. Pricing is public.


 App of the Year
