

Summary
Cash flow management is tracking, forecasting and controlling the cash moving in and out of a business so bills get paid on time even when profit looks fine on paper. The fastest lever for most small businesses is collecting receivables faster, since unpaid invoices are the most common cause of a cash shortfall.
- The three flows: Cash flow splits into operating (day-to-day sales and costs), investing (buying or selling assets) and financing (loans and repayments), and a forecast needs all three.
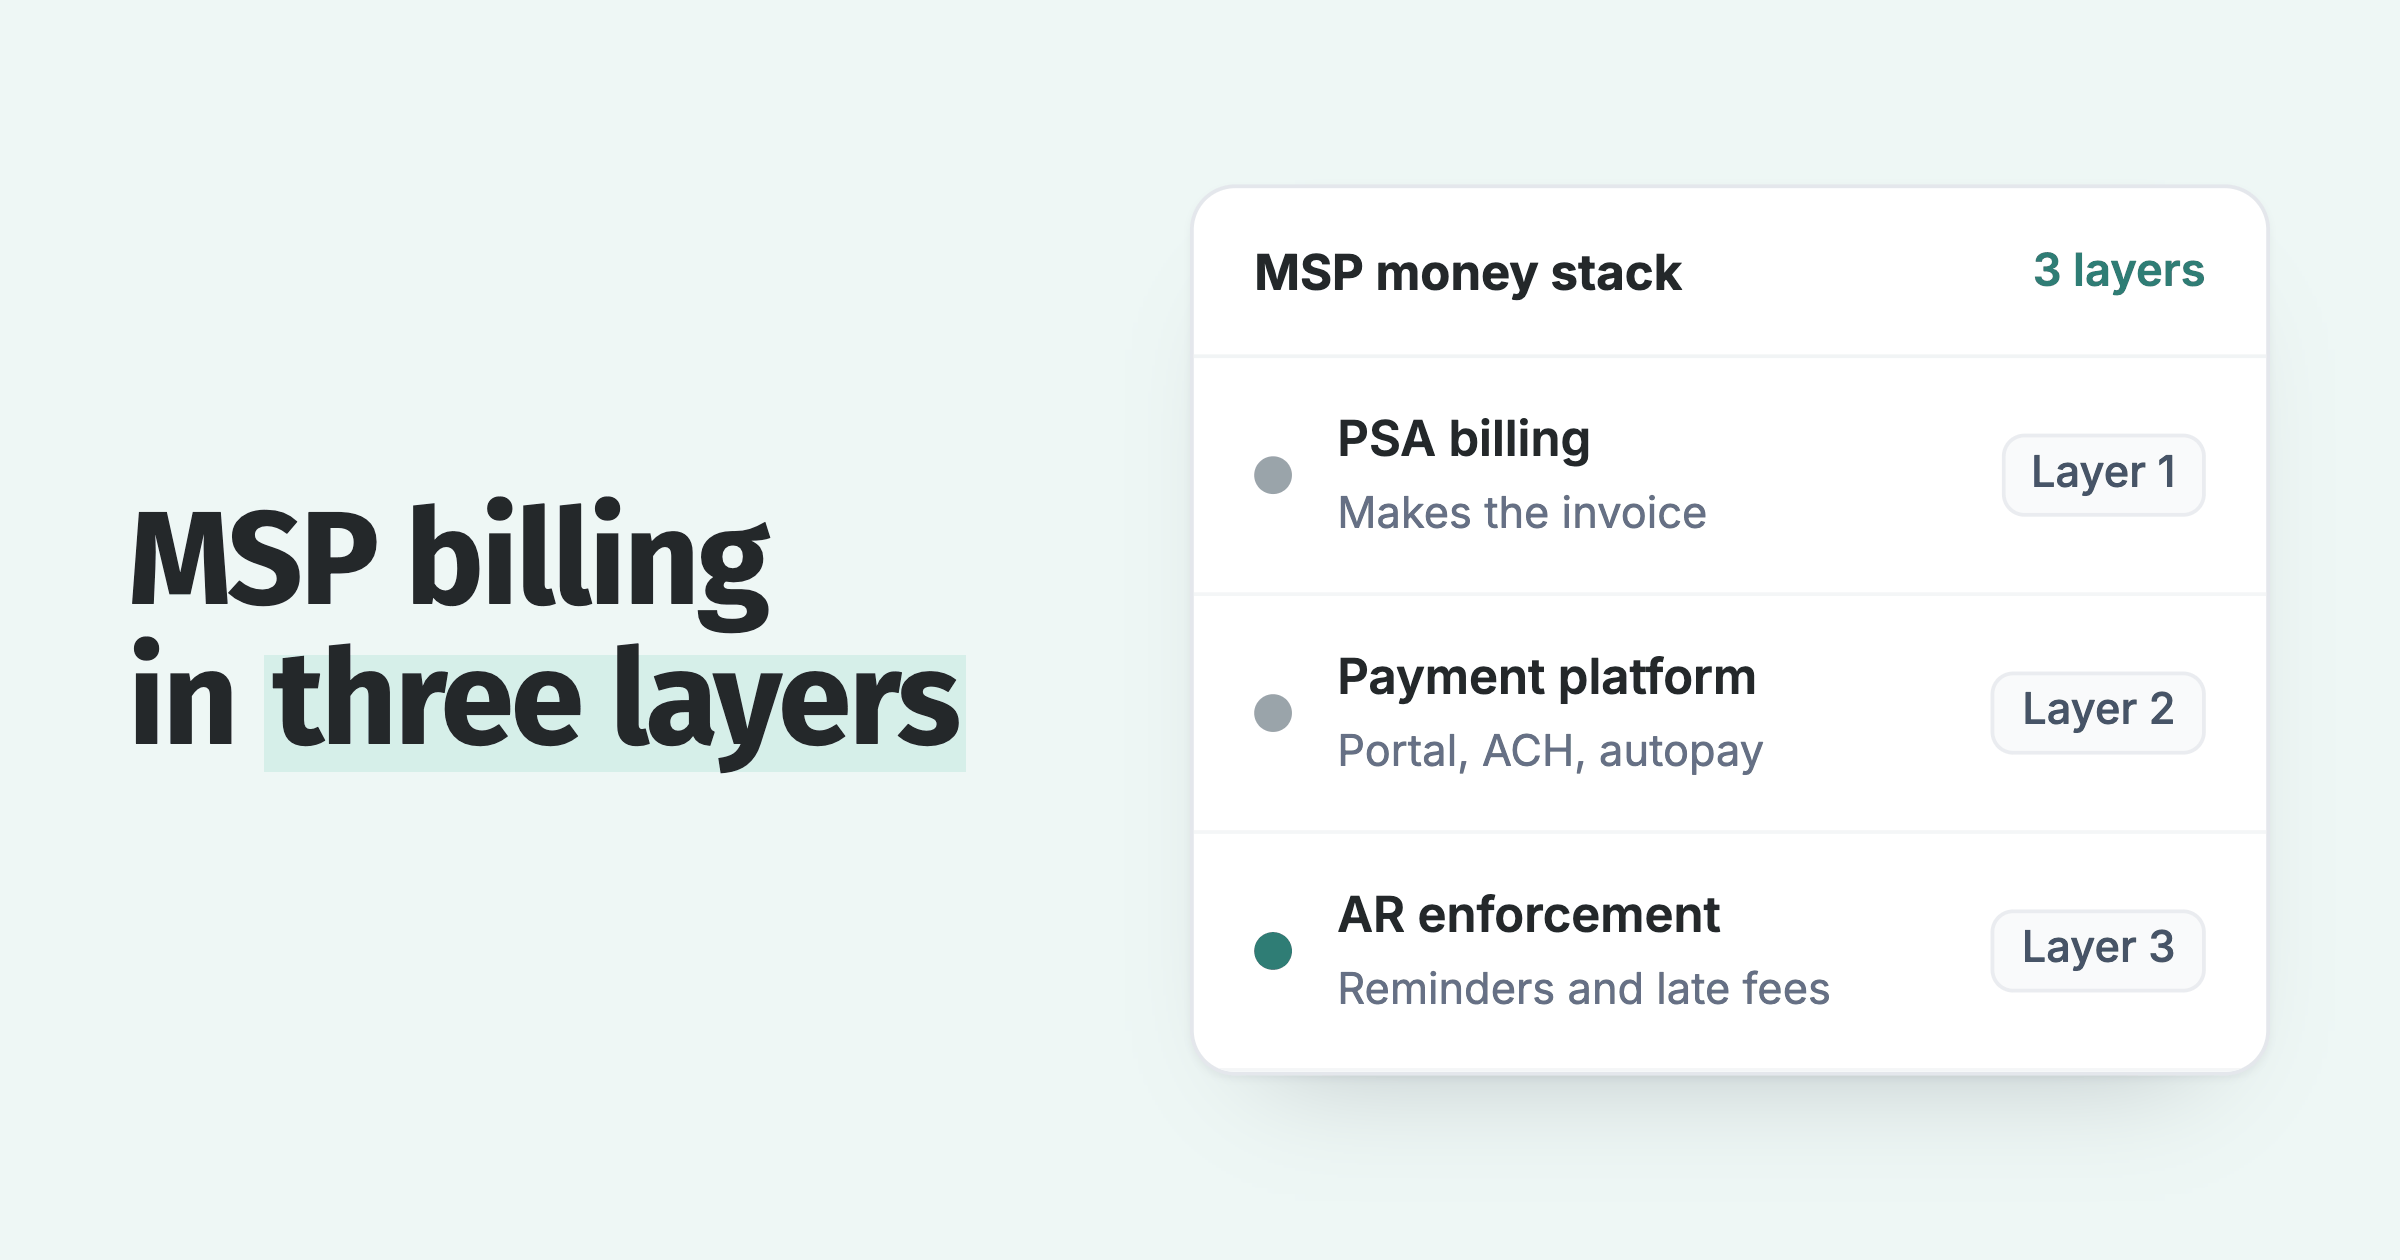
- The AR lever: Paidnice automates invoice reminders, late fees and interest, statements and payment plans on Xero and QuickBooks Online, so a business collects faster without a manual chasing process.
- The buffer rule: A cash reserve covering 3 to 6 months of operating expenses is the standard advice for absorbing a late-paying customer or a seasonal dip.
What is cash flow management?
Cash flow management is the process of tracking, forecasting and controlling the cash moving into and out of a business so it can meet its obligations without running short. Profit is an accounting figure; cash is what pays wages on Friday, and a profitable business can still miss payroll if its customers pay late.
Free: Payment reminder email templatesCopy the reminder emails for before, on and after the due date.A business has three kinds of cash flow, and a forecast needs all of them:
- Operating cash flow is the cash from day-to-day trading: customer payments in, suppliers, wages and rent out.
- Investing cash flow is cash spent on or received from long-term assets such as equipment, vehicles or property.
- Financing cash flow is cash from loans, owner contributions and their repayments.
Operating cash flow is the one a small business controls week to week, and within it the timing of customer payments is the biggest variable.
How do you track cash flow over time?
Businesses track cash flow with a cash flow statement, a report that shows cash moving into and out of the business over a set period, updated on a fixed schedule such as weekly or monthly.
Accounting software such as Xero or QuickBooks Online produces the statement from the ledger, and a spreadsheet works for a very small business. Either way, record the source and reason for each cash movement so the statement explains itself to an accountant or lender. A statement reviewed on the same day each week shows a dip forming three or four weeks out, which is enough time to chase invoices or delay a purchase. For the forward-looking version, see the cash flow forecast definition.
Which cash flow metrics matter most?
The average collection period, net operating cash flow and inventory turnover are the three metrics that show whether a business is collecting and spending cash on a healthy schedule.
- Average collection period is how long customers take to pay. Divide average accounts receivable by credit sales for the period, then multiply by the days in the period. A 30-day term with a 45-day collection period means the business is lending its customers two extra weeks of cash.
- Net operating cash flow is the cash left from trading after operating costs are paid. Negative for more than a month or two means the business is funding itself from reserves or debt.
- Inventory turnover is how often stock sells through in a period. Slow turnover is cash sitting on a shelf.
The average collection period is the metric automated reminders and late fees are built to shorten. Paidnice customers see half as many late invoices in the first 30 days.
How do you collect receivables faster?
The fastest way to improve cash flow is shortening how long customers take to pay, through clear payment terms, automated reminders before and after the due date, and a late fee or interest charge that makes on-time payment the easy choice.
Xero Small Business Insights puts the UK average wait to be paid at 29.1 days in the June 2026 quarter, 8.3 days past due.
The steps, in the order they pay back:
- Put the terms on every document. Due date, late fee or interest policy, and payment methods on the quote, the contract and the invoice. Take a deposit or payment upfront where the work allows it.
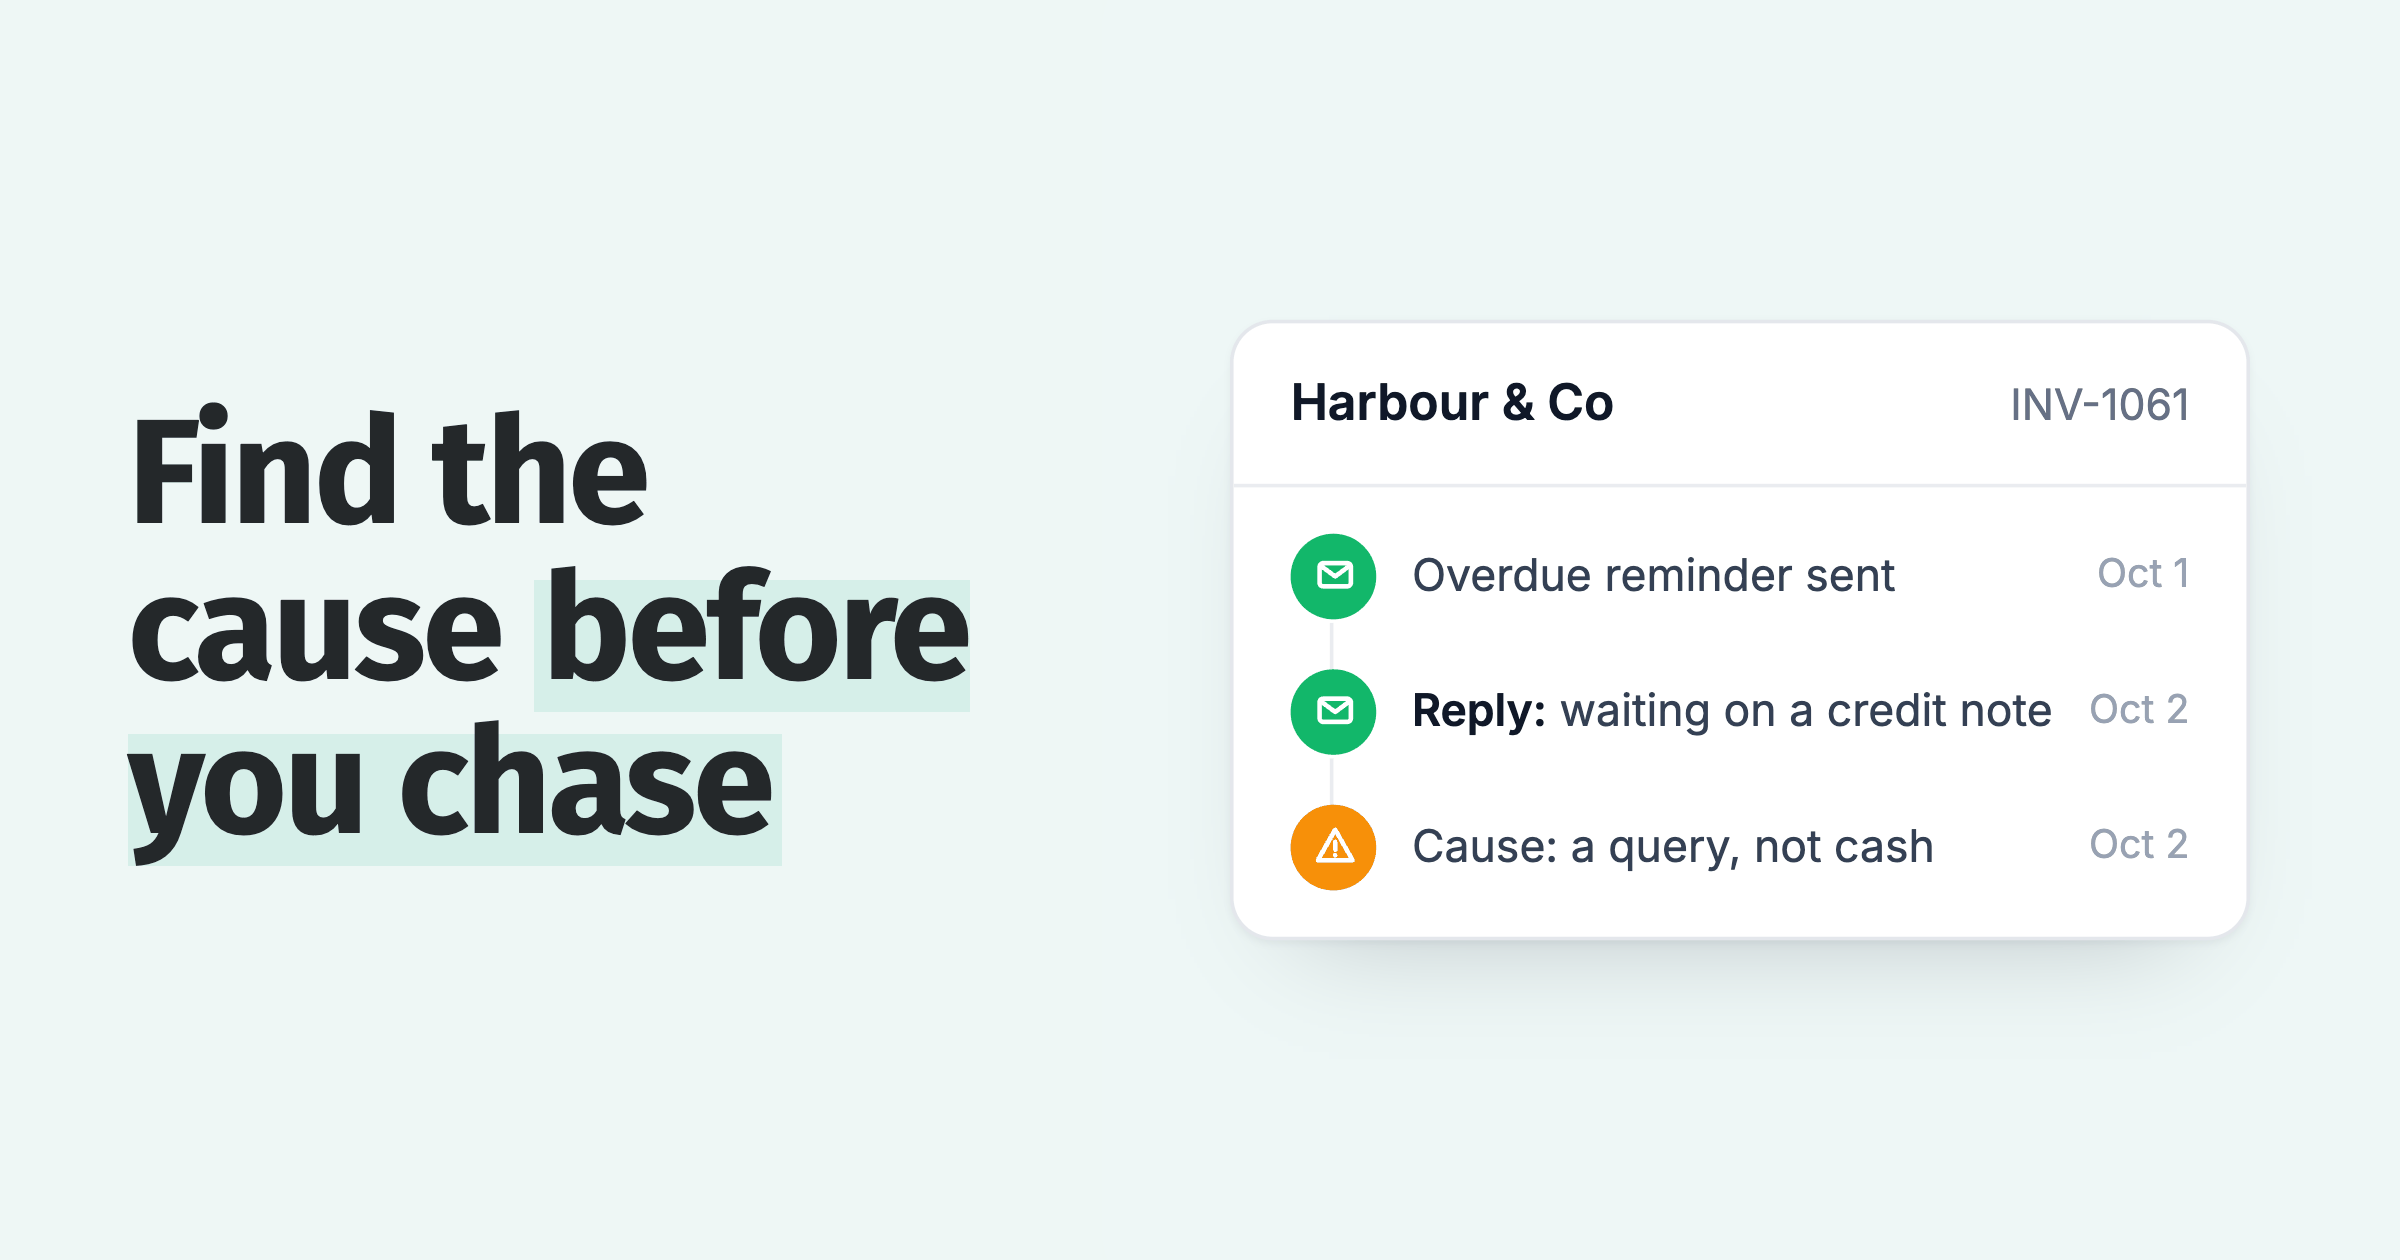
- Remind before the due date, then the day after. A reminder a few days before due catches the forgetful; one the day after signals the date was real. Email for the paper trail, SMS for customers who do not open email.
- Add a cost to lateness. A late fee or interest charge stated on the invoice moves yours up the customer's payment run. Post it to the ledger so the statement shows one balance.
- Send statements on a schedule. Bookkeepers reconcile to statements, so a monthly statement with every open invoice gets the whole balance into the payment run.
- Offer a payment plan early. A customer who cannot pay in full pays something on fixed dates, with autopay, instead of nothing.
Paidnice runs all five from the invoices already in Xero or QuickBooks Online: reminders by email and SMS, late fees and interest posted to the ledger, statements recalculated at the moment they send, and payment plans with autopay. Signing up is free with no card, and the first 20 actions are free.
How big should a cash flow buffer be?
A cash flow buffer of 3 to 6 months of operating expenses is the standard reserve for absorbing a late-paying customer, a slow season or an unplanned cost, held in an account separate from day-to-day trading.
Build it from a fixed monthly transfer rather than whatever is left over, and size it to the business's own risk: a firm with two customers making up half its revenue needs the top of that range, a business paid at the till can hold less. Insurance premiums, repairs and tax bills are predictable, so list them with dates in the forecast.
What is a good cash flow for a business?
A good cash flow is a positive net cash flow every month, where cash from sales and receivables consistently exceeds cash going out to payroll, suppliers and debt repayments, with enough left over to build a 3 to 6 month buffer.
There is no single healthy number. It depends on the business's size, its customer payment terms and its fixed costs, so the more useful check is the trend: flat or improving over several months is healthy, declining is the signal to act.
Do small companies need a cash flow statement?
Yes. A cash flow statement matters most for small companies, because a single late-paying customer or an unplanned expense can create a shortfall even when the business is profitable on paper, and the statement is the only report that shows cash position directly rather than accounting profit.
A small business rarely has a finance team or a credit line to cover a gap, so the statement is its early warning: it shows the shortfall forming while there is still time to collect an invoice or defer a purchase.
About the editorial team
Denym started Paidnice in 2022 after customers paying late left his own business short on payroll. He has led it to $1 billion collected on time across more than 1 million invoices, and writes about credit control, late fees and getting paid on Xero and QuickBooks.
 App of the Year
